
Susi Air, an Airline Born Out of Logistical Challenges
Imagine a seafood business giving birth to an airline. The problem was simple but costly: fish lose freshness and value during a long journey. In the early 2000s, the road trip from Pangandaran to Jakarta was too slow for Susi Pudjiastuti's seafood business. Rather than accept the problem, she bought two Cessna Caravans to shorten the delivery chain. What began as a logistics solution later became Susi Air. The aircraft purchase was recorded in February 2004, before PT ASI Pudjiastuti Aviation began operating at the end of that year [1].
A Plane for Fish, then Planes for Indonesia
At first, Susi was not trying to build a national passenger airline. The aircraft supported her seafood-export business. The Aceh earthquake and tsunami in December 2004, however, revealed a broader purpose. Two Susi Air aircraft were based in Medan and flew relief organizations into affected areas. The business grew from there. In 2006, Susi Air began developing scheduled services. Its website reports 48 aircraft, 20 operating bases, around 120 daily flights, more than 500 domestic routes, and 304 scheduled destinations [2].
This is where Susi Air's entrepreneurial story becomes especially interesting. Susi did not begin by asking which industry was fashionable. She focused on a real problem and made better use of assets already under her control. Aircraft that had originally protected the freshness of fish also proved useful for pioneer flights, charters, urgent freight, medical evacuations, aerial surveys, and specialist travel. This was not random expansion. Every service relied on the same strengths: small aircraft, pilots and technicians comfortable in difficult terrain, and a network of bases close to remote communities [3].
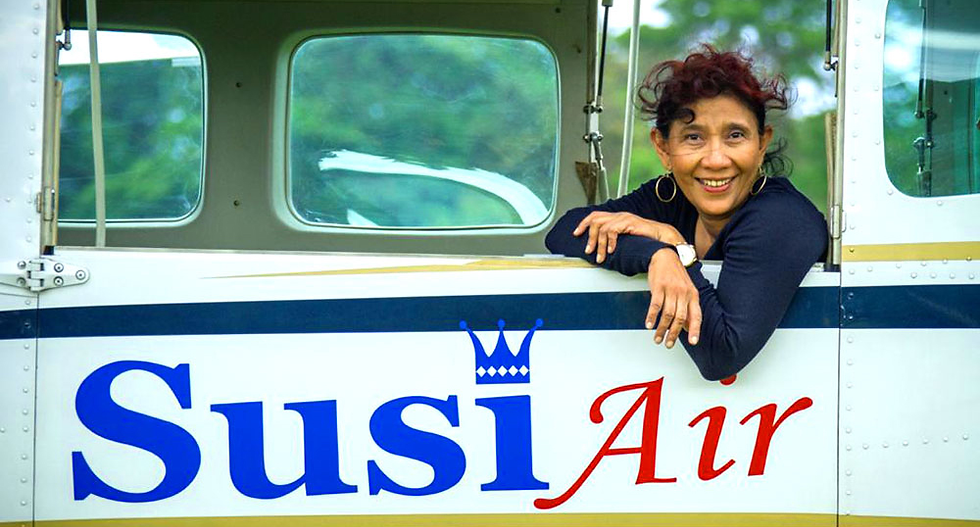
Why Susi Air Matters
Susi Air's role goes well beyond the tickets it sells. For many underdeveloped, frontier, outermost, and border regions, small aircraft provide a link to healthcare, education, trade, tourism, and government services. In 2025, Indonesia's pioneer aviation program covered 266 passenger routes and 46 cargo routes, with PT ASI Pudjiastuti Aviation among the operators. The Transportation Ministry also sees the program as a way to open access, support regional economies, and reduce price differences between areas [4].
Viewed through an entrepreneurial lens, the story offers three straightforward lessons. First, limitations can create opportunities for innovation. Short runways, low passenger volumes, and difficult geography may not suit large jets, but they create a clear role for small turboprops. Second, one asset can support more than one business. A fleet purchased for an internal supply chain grew into a platform for several services. Third, social purpose and commercial returns do not always have to compete. Pioneer contracts and charter work can help fund connectivity on routes that are not yet large enough to stand on their own, although reliance on annual tenders remains a risk to watch [4][5].
What Might Susi Air be Worth?
Susi Air's operating-business value could be estimated using EV/EBITDA. This method suits Susi Air because it combines regional, pioneer, and charter operations, linking its value to the operating profit the business can generate without being affected by the company's debt structure.
The calculation uses ZoomInfo's estimate of US$58.4 million in annual revenue. The revenue is converted into EBITDA using three margin assumptions and then multiplied by an EV/EBITDA multiple. The conservative scenario uses a 10% margin and a 4.5 times multiple, producing approximately US$26 million. The central scenario uses a 15% margin and a 5.5 times multiple, producing approximately US$48 million. The optimistic scenario uses a 20% margin and a 6.5 times multiple, producing approximately US$76 million. Because the revenue figure is a third-party estimate, the results are indicative [6].
At the 14 August 2026 JISDOR rate of Rp17,836 per US dollar, the values are equivalent to approximately Rp469 billion to Rp1.35 trillion, with a central scenario of about Rp859 billion. The 48-aircraft fleet, 20 operating bases, licences, technicians, pilots, and route network are used as a reasonableness check. The fleet is not valued using one aircraft price because each aircraft differs in type, age, condition, ownership, and lease obligations [2][7].

These figures represent enterprise value, or the value of the operating business. Equity value can only be calculated after deducting debt and lease obligations and adding surplus cash and non-operating assets. Because those figures are not publicly available, the estimate stops at enterprise value.
Ultimately, Susi Air's biggest lesson is much simpler: pay attention to problems that others have learned to accept. Susi Air began when a freshness problem became an investment decision, then grew when those aircraft were used to meet Indonesia's need for connectivity. Its value therefore lies not only in the aircraft it owns, but also in its ability to turn distance into a market and isolation into access.
References
[1] FlightGlobal; "Fresh fish to market via Cessna Caravan"; February 25, 2004; https://www.flightglobal.com/strategy/fresh-fish-to-market-via-cessna-caravan/53201.article
[2] Susi Air; "About: Susi Air at a Glance"; accessed August 18, 2026; https://susiair.com/about
[3] Susi Air; "Our Services"; accessed August 18, 2026; https://susiair.com/
[4] PwC Indonesia, translating Investor Daily; "Transportation Ministry continues pioneer air transportation programme in 2025"; January 17, 2025; https://www.pwc.com/id/en/media-centre/infrastructure-news/january-2025/air-transportation-programme-in-2025.html
[5] Kontan; "Susi Air to buy 16 aircraft worth US$100 million"; April 13, 2012; https://english.kontan.co.id/news/susi-air-to-buy-16-aircraft-worth-us100-million
[6] ZoomInfo; 'Susi Air Overview'; accessed September 11, 2026; https://www.zoominfo.com/c/susi-air/346711735. The US$58.4 million revenue estimate is third-party data and has not been verified against audited financial statements.
[7] Bank Indonesia; 'JISDOR'; August 14, 2026; https://www.bi.go.id/en/statistik/informasi-kurs/jisdor/default.aspx. Reference rate: Rp17,836 per US dollar.
Disclaimer: This content is created for educational purposes or service promotion, and does not constitute a recommendation to buy or sell any specific Securities. Any risks arising from investment decisions made based on the information in this publication are the sole responsibility of the respective audience. PT KAF Sekuritas Indonesia is licensed and supervised by the Financial Services Authority (Otoritas Jasa Keuangan / OJK).
Comments